Wealtie logoWealtie

Money & budgeting blog: Plain answers, sources included

Straight answers to everyday money questions: how much to save, how to set a budget you'll keep, what to do when your pay changes from month to month. Every post works through real numbers and shows where they come from.
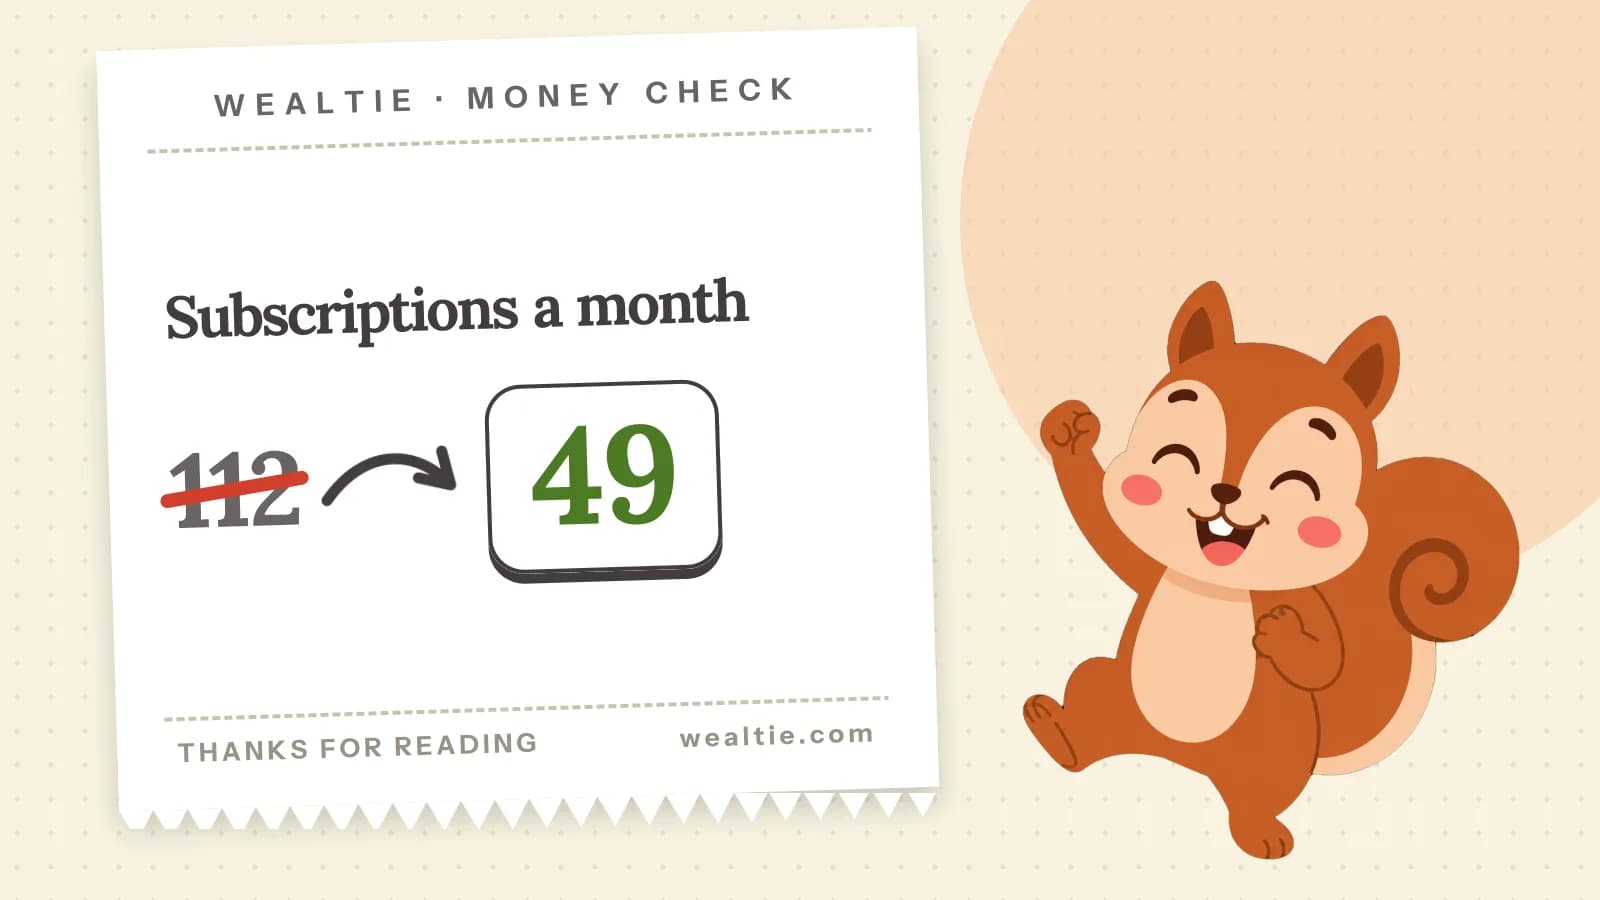
  • Wally celebrating beside a receipt: subscriptions cut from 112 to 49 a month in a worked example.
    BUDGETING

    How to cut subscription costs: a 30-minute audit and what to keep

    To cut subscription costs, list every recurring charge from three months of statements, then decide for each one: keep, downgrade, pause or cancel. Rotating streaming services instead of paying for all of them at once, and switching the ones you keep to yearly billing, usually cuts the total without losing much.

    · 3 min read

  • Wally giving a thumbs up beside −5.0%: US car insurance prices fell 5.0% in the year to September 2026.
    BUDGETING

    How to save money on car insurance while prices are falling

    The best way to save money on car insurance in 2026 is to compare quotes at every renewal: prices fell 5.0% in the year to September, according to the BLS, so last year's premium may now be above the market. Then raise your deductible if your savings can cover it, and check every discount.

    · 3 min read

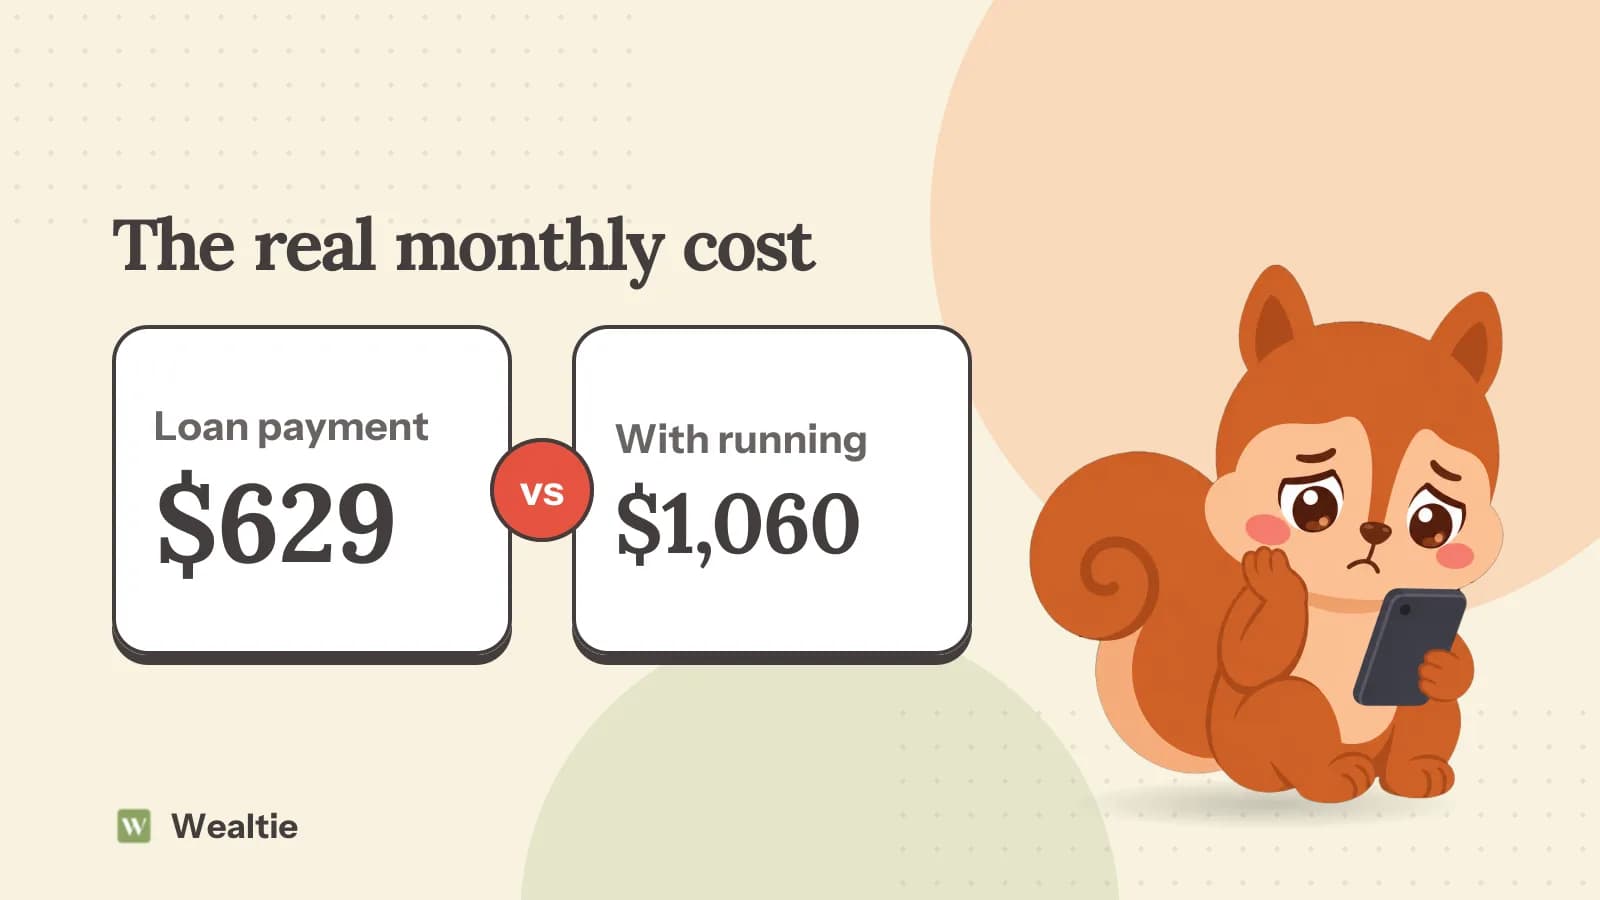
  • Wally looking worried beside 'The real monthly cost': a $629 loan payment becomes about $1,060 a month with insurance, fuel and maintenance.
    BUDGETING

    How much car can I afford? The payment, the full cost and a table

    The car you can afford is the one whose full monthly cost, loan payment plus insurance, fuel and upkeep, fits your budget alongside rent and savings. With the average new car at $50,562 and new car loans averaging 9.45% in September 2026, a $30,000 loan over 60 months costs about $629 a month before anything else.

    · 3 min read

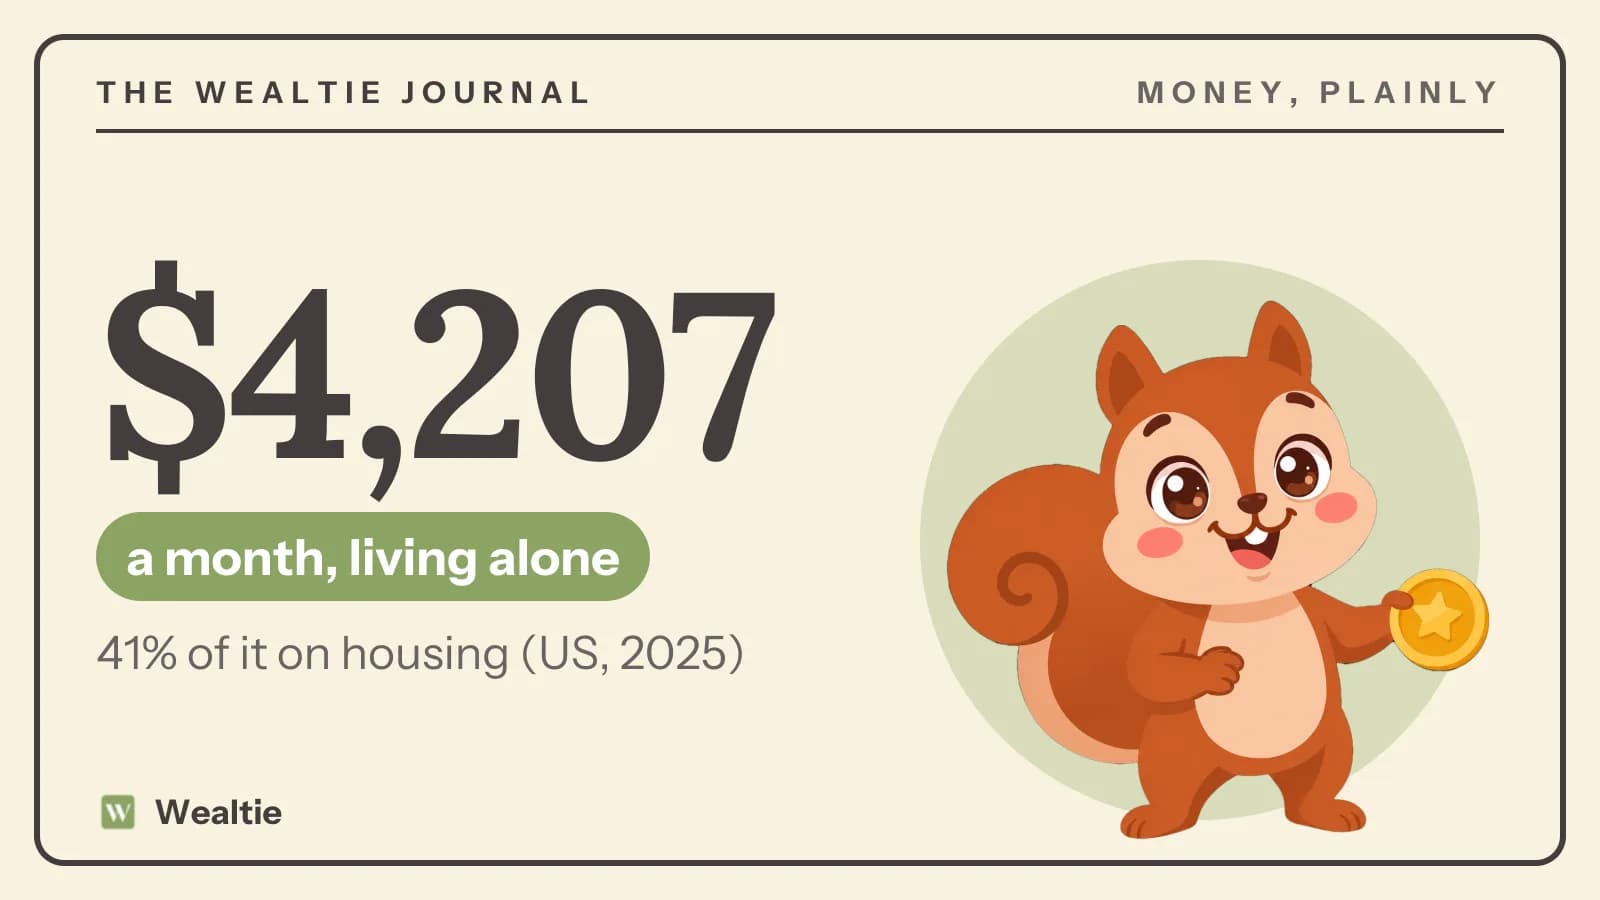
  • Wally holding out a coin beside $4,207 a month, the average spending of a one-person US household in 2025, 41% of it on housing.
    BUDGETING

    Average monthly expenses for one person: the 2025 numbers

    The average monthly expenses for one person living alone in the US were about $4,207 in 2025, according to the Bureau of Labor Statistics: $50,479 for the year. Housing took $1,708 a month, 41% of the total, followed by transport at $592 and food at $474.

    · 3 min read

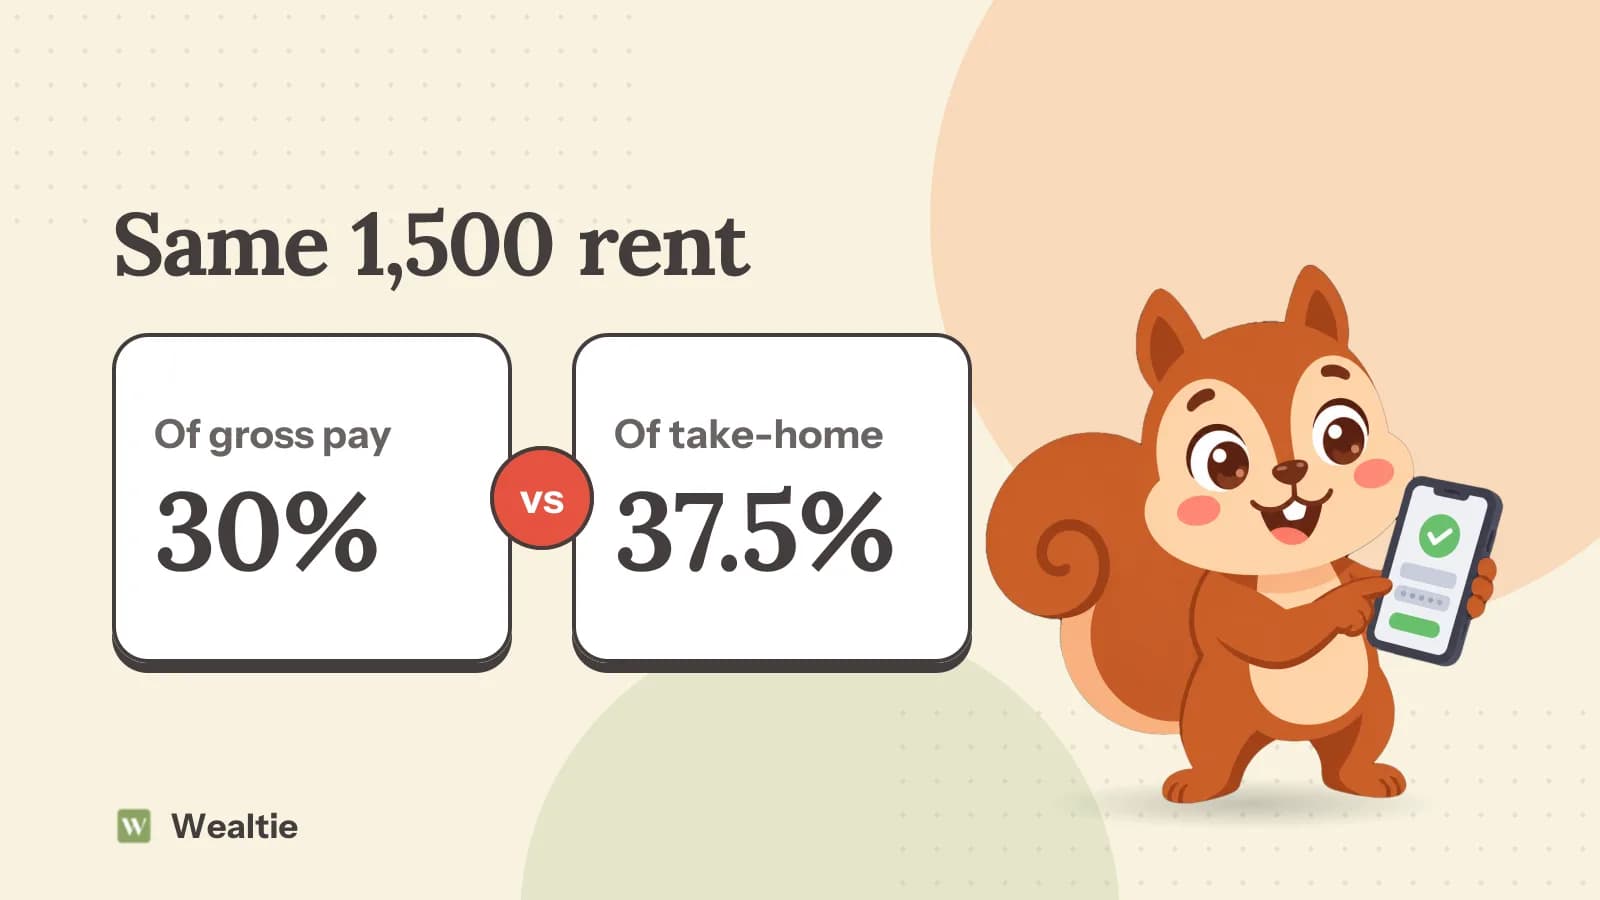
  • Wally checking his phone beside 'Same 1,500 rent': 30% of gross pay is 37.5% of take-home pay.
    BUDGETING

    How much rent can I afford? A rule, a table and the budget check

    A common answer to how much rent can I afford is 30% of gross income. A safer test uses take-home pay: keep rent to about 25% to 30% of what reaches your account, then check that rent, bills, groceries and debt payments together fit in half of it. On 4,000 a month take-home, that's rent of 1,000 to 1,200.

    · 3 min read

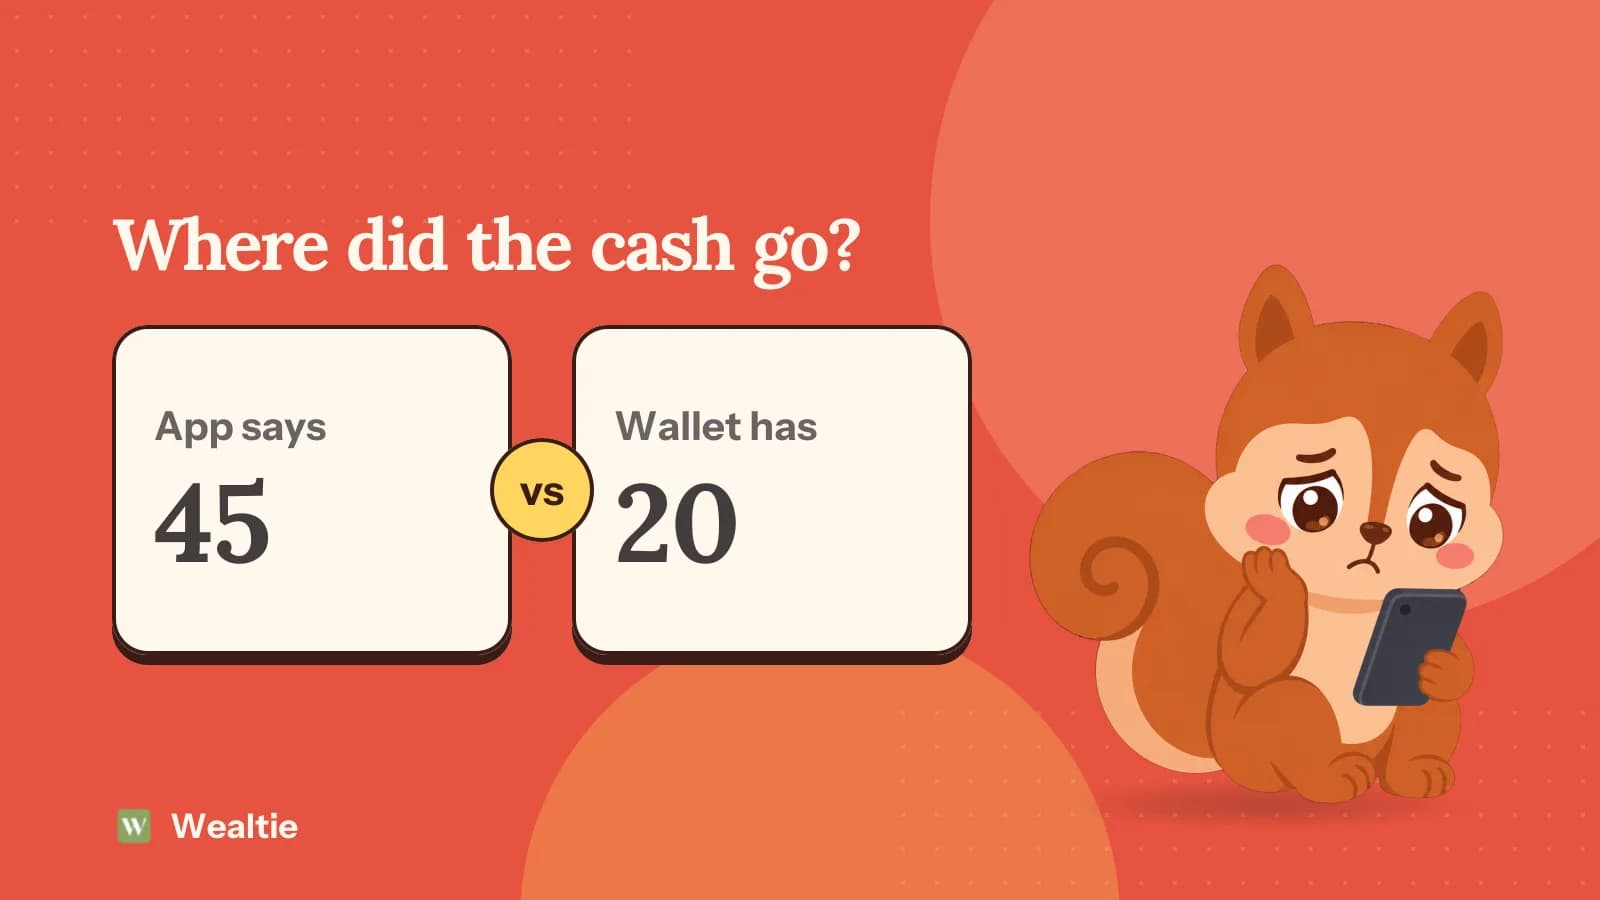
  • Wally looking worried beside 'Where did the cash go?': the app says 45, the wallet has 20.
    USING WEALTIE

    How to track cash spending the same way as your card

    To track cash spending, treat your wallet as an account: an ATM withdrawal is a transfer into it, not spending, and each cash purchase is logged from it as it happens. Once a week, count the cash and compare it with the wallet's balance; the difference is spending you forgot.

    · 3 min read

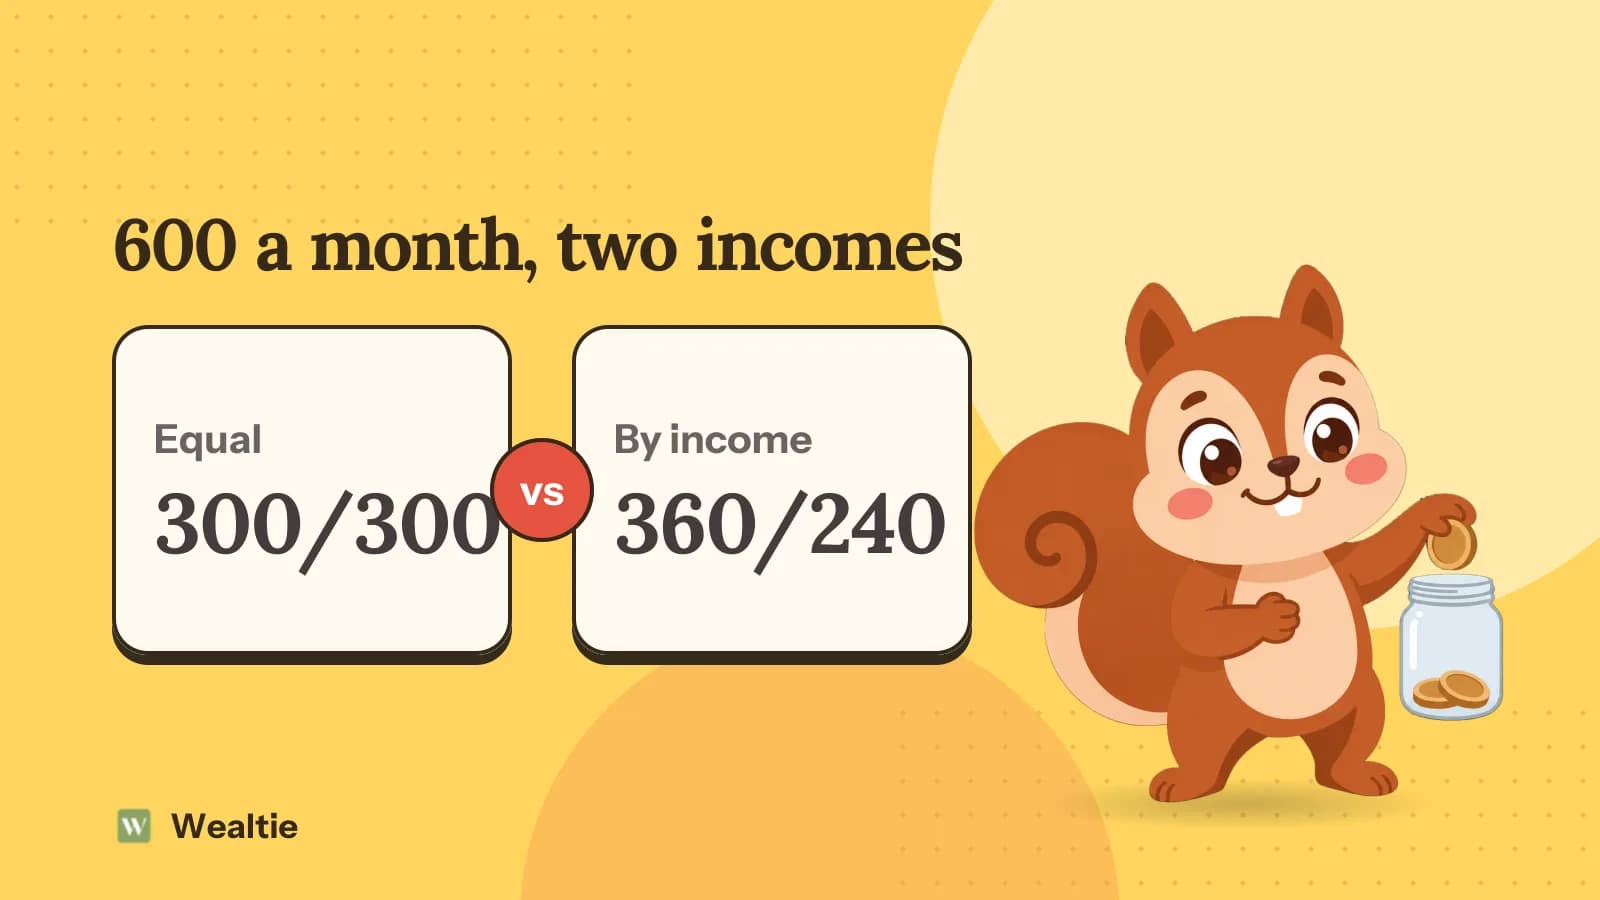
  • Wally dropping a coin into a jar beside '600 a month, two incomes': equal 300 and 300, or by income 360 and 240.
    MONEY AS A COUPLE

    Saving for a goal together when you earn different amounts

    Saving for a goal together starts with a target, a date and a monthly amount you both agree on. When you earn different amounts, contributing the same share of each income, rather than the same sum, keeps the goal fair. Keep the money in its own account and agree upfront what happens to it if plans change.

    · 3 min read

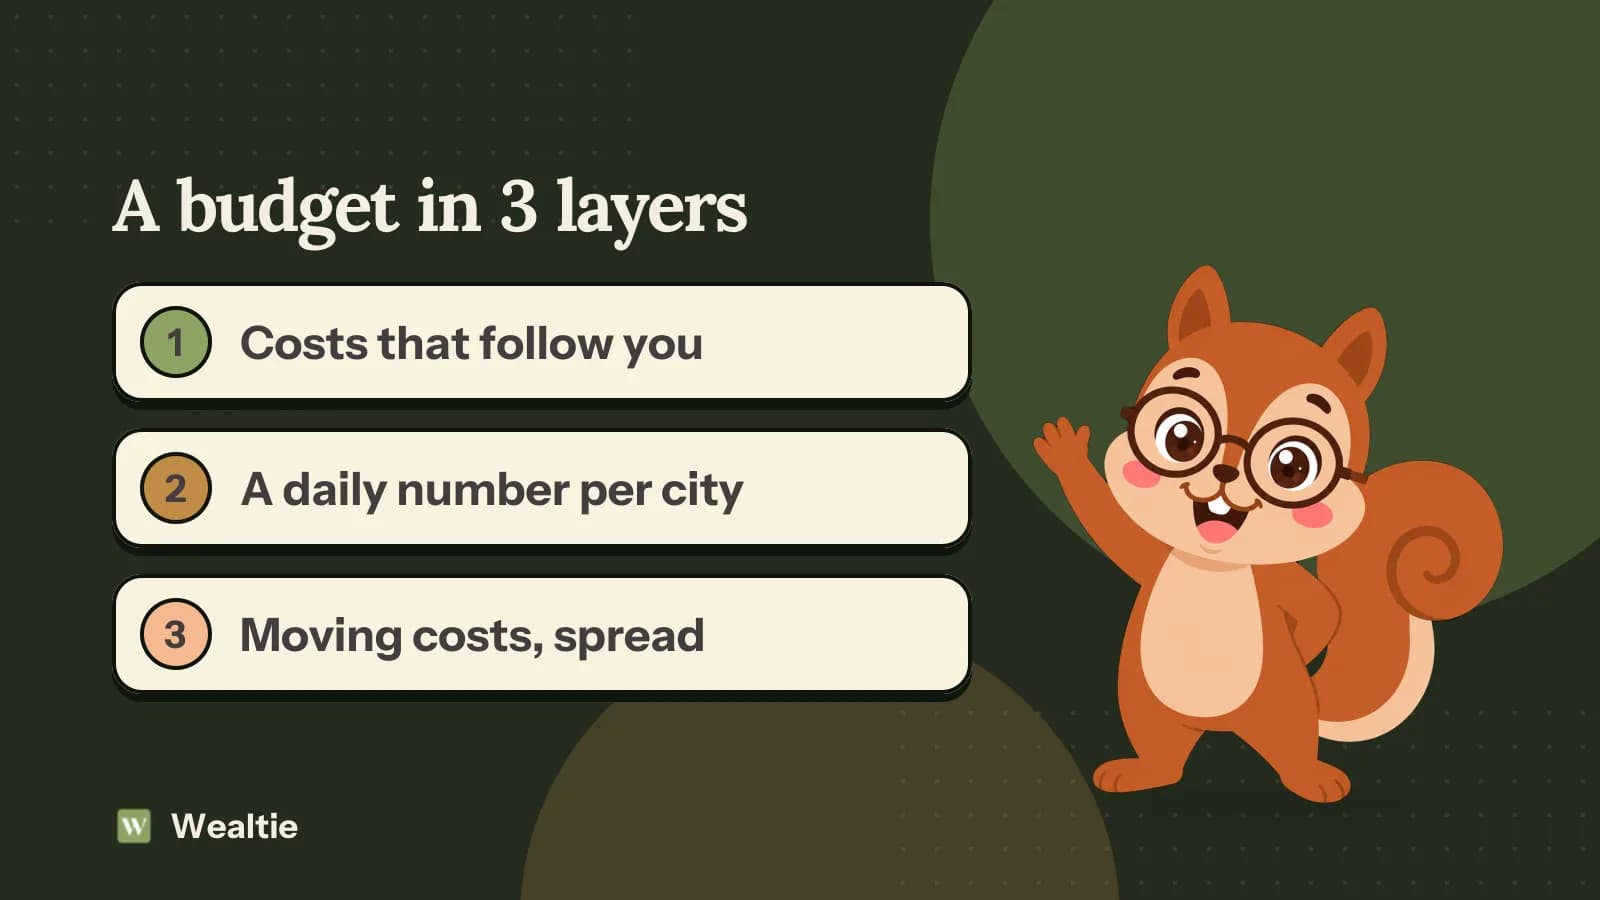
  • Wally waving beside 'A budget in 3 layers': costs that follow you, a daily number per city, moving costs spread out.
    MULTI-CURRENCY & TRAVEL

    A digital nomad budget that survives changing countries

    A digital nomad budget works in three layers: costs that follow you everywhere, like insurance and subscriptions; a daily spending number that resets in each country; and the cost of moving between bases. Budget in the currency you earn, set a monthly total, and let the daily number change with each place.

    · 3 min read

  • Wally checking his phone beside 'One paycheck, two countries': paid in euros, mortgage in pounds.
    MULTI-CURRENCY & TRAVEL

    Budgeting as an expat: two countries, two currencies, one total

    Budgeting as an expat works best in the currency you're paid in, with a separate line for every cost that's still in your home currency: a mortgage, family support, insurance or savings. Convert those at a planned rate, keep a small cushion for exchange swings, and look at both countries in one total.

    · 3 min read

  • Wally checking his phone beside 20%, the typical swing from average in a worked example: put a number on uneven pay.
    INCOME & FREELANCING

    How to measure income stability: put a number on uneven pay

    To measure income stability, take your last 12 months of income and work out three numbers: the lowest normal month, the average, and how far a typical month strays from the average. The smaller that spread, the steadier your income, and the less you need in a buffer to budget on it.

    · 3 min read

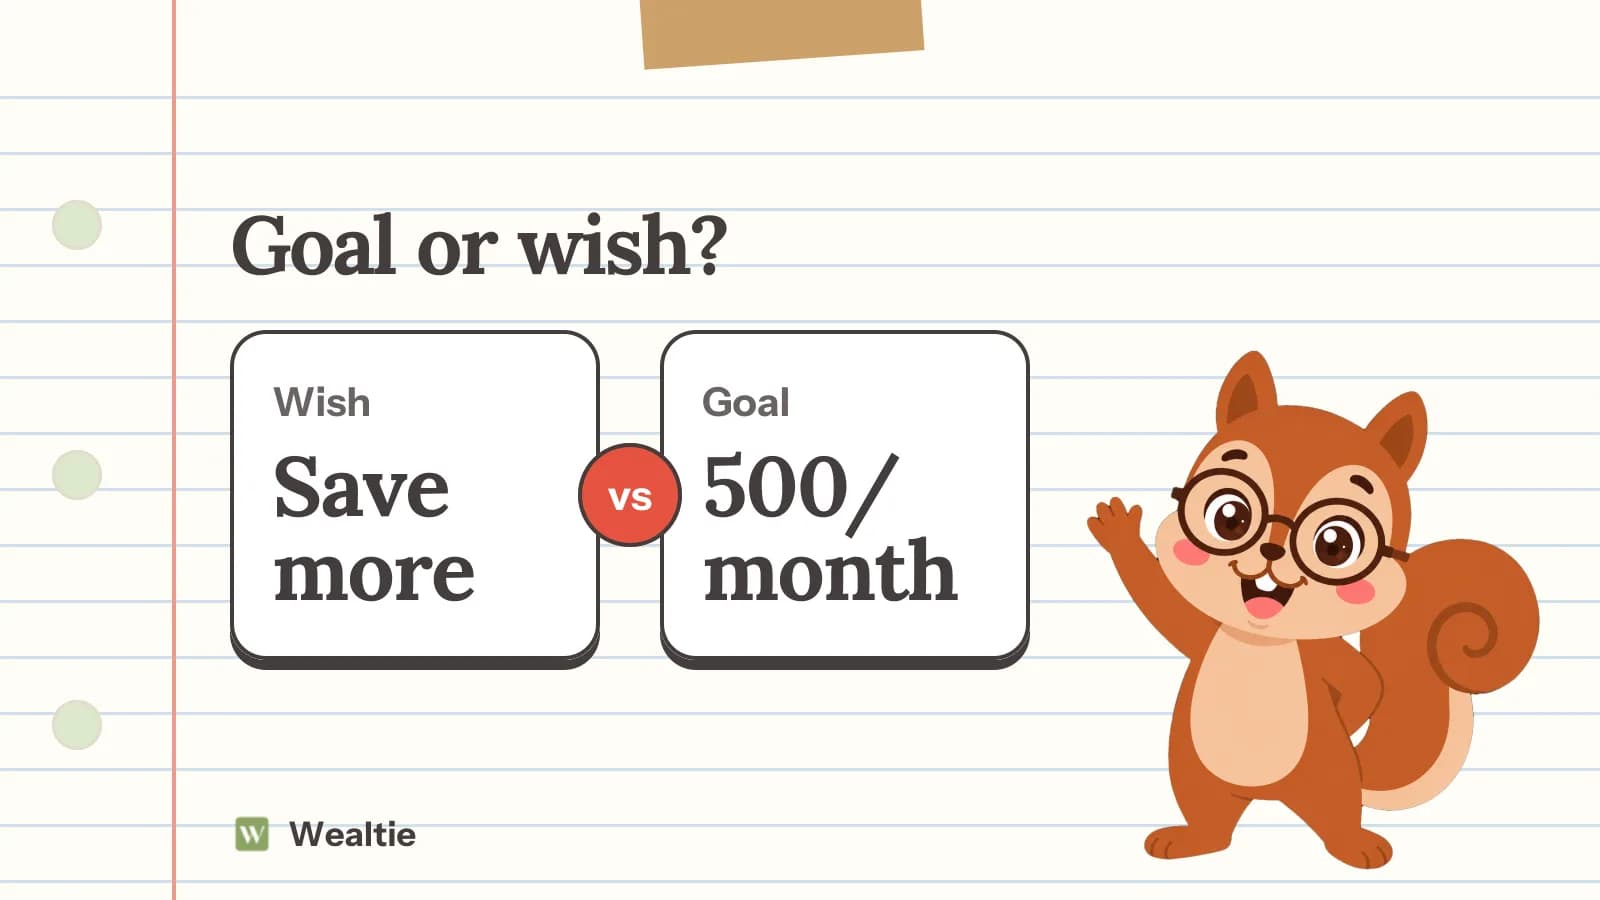
  • Wally waving beside a notebook: 'Goal or wish?' Save more is a wish; 500 a month is a goal.
    SAVING

    How to set financial goals for 2027 that you'll still have in March

    To set financial goals, pick one or two for the year, give each a number, a date and a monthly amount, and move that amount automatically on payday. "Save more" isn't a goal; "save 3,000 by July, 500 a month" is. Order matters too: a small emergency fund comes before almost everything else.

    · 3 min read

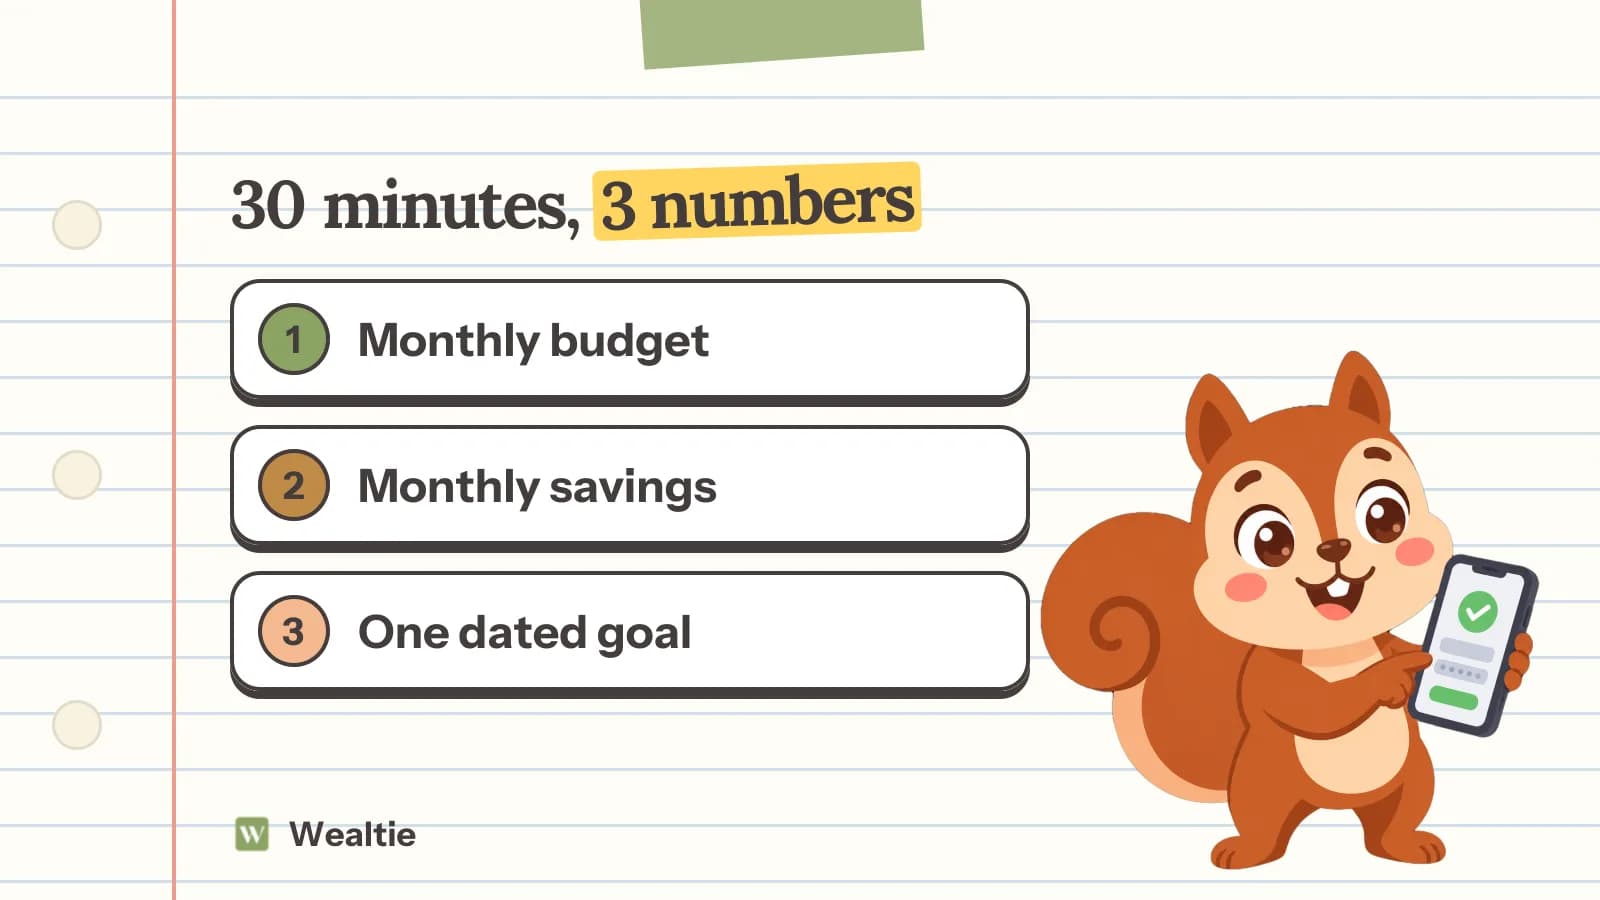
  • Wally checking his phone beside a notebook: 30 minutes, 3 numbers. Monthly budget, monthly savings, one dated goal.
    BUDGETING

    Year-end money review: 30 minutes to check the year and set the next

    A year-end money review takes about 30 minutes: add up the year's income and spending, find the three biggest surprises, check savings and debt against where you started, and set next year's budget and goals from the real numbers. Do it in the last week of December, before January's bills arrive.

    · 3 min read

The weekly email

New posts, once a week

Once a week, the new posts on budgeting, saving and everyday money. Nothing else, and one click to leave.

Money & Budgeting Blog, page 4 | Wealtie